 By
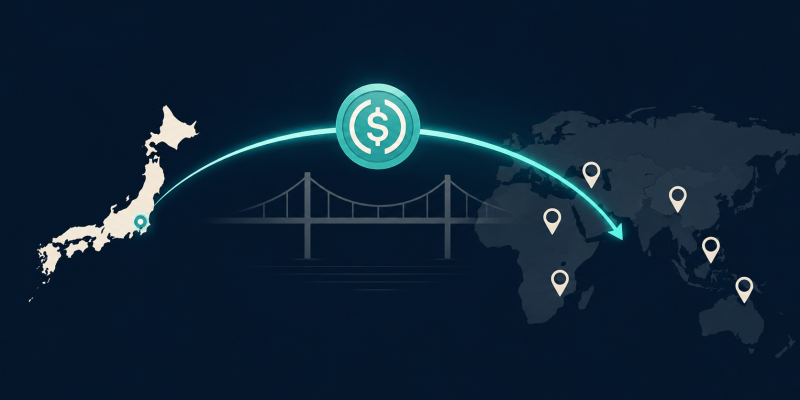
Fasset has joined a growing club of stablecoin startups that turned into unicorns almost overnight. The Los Angeles company, which runs a stablecoin-powered neobank aimed at emerging markets, said it raised $68 million in a Series C led by Japan’s SBI Group at a $1 billion valuation. What makes the round stand out is the timing: it lands just three months after Fasset’s $51 million Series B, taking its haul for the year to $119 million and its total funding past $150 million.
Founded in 2019 by Mohammad Raafi Hossain and Daniel Ahmed, Fasset lets people and businesses in places like Pakistan, Türkiye, Indonesia, and the Gulf hold, move, and invest money across currencies and assets, with stablecoins as the settlement layer underneath. The pitch is straightforward and useful: in markets where the local currency is shaky and traditional cross-border transfers are slow and costly, a dollar-pegged token that moves in minutes solves a real problem. Its underlying rail, called Own Network, now stretches across more than 100 banking corridors, and the platform processes about $40 billion in annualised transaction volume across 3 million wallets.
Why SBI is the key backer
The lead investor matters more than the headline number. SBI is one of Japan’s largest financial groups, with stakes in Ripple, Circle, and other crypto infrastructure, and it is building what it calls an Asia-Pacific digital economic zone with stablecoin remittance at its core. For Fasset, that unlocks SBI Remit, a network reaching bank payouts in around 200 countries. In other words, SBI is not just writing a cheque, it is handing Fasset distribution into corridors that would take years to build alone. One quietly notable detail: Fasset runs a Shariah-compliant model, which has helped it gain real traction across the Gulf and South Asia, where interest-free finance is a requirement, not a preference.
The numbers to watch, and the ones we cannot see
Here is where a little scrutiny is healthy. That $40 billion figure is transaction volume, the money flowing through the pipes, not revenue. Fasset’s chief executive told CoinDesk that revenue has grown roughly six-fold in a year and that the company has been profitable for twelve straight months, which would be rare for a neobank. The catch is that Fasset disclosed neither its revenue nor its profit, so the $1 billion valuation is being taken partly on faith.
There is also a structural question hanging over every business like this. The whole appeal of stablecoin rails is that moving value costs almost nothing, which is wonderful for customers but brutal for anyone trying to earn fees on the transfer. As one observer put it, stablecoin neobanks face real margin compression precisely because the transfers are so cheap. Fasset’s answer is to make money elsewhere, on investing, lending, and institutional services, but that is a harder business than moving money.
None of this is unique to Fasset. Stablecoin startups have been minting unicorns all year, from Rain to Slash, as the sector’s total supply blew past $270 billion. That is a tailwind and a warning: the opportunity is real, but so is the crowd chasing it, and valuations are running well ahead of proven economics.
So has Fasset built the future of emerging-market banking, or caught a very generous wave? For now, both look true. It has a real problem to solve, a powerful new partner, and rare claimed profitability. Whether it can turn $40 billion in flow into a durable business is the test the next year will set.

Comments