 By

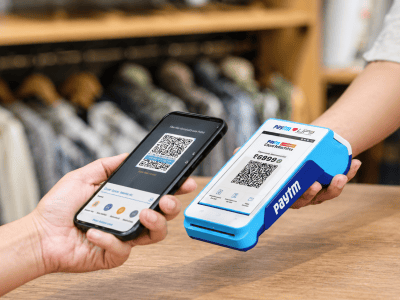
Digital lending company Fibe has launched UPI payments within its app after receiving approval from the National Payments Corporation of India to operate as a third-party application provider. The launch, announced on November 2 and reported on November 3, marks the company’s expansion from lending and credit products into everyday digital payments.
The service is open to users across India, including customers who do not have an existing loan or credit relationship with Fibe. The move gives the company an opportunity to build a broader consumer payments business while connecting its existing financial products with routine transactions.
UPI Access Beyond Existing Borrowers
Fibe users can make payments through a linked bank account, a RuPay credit card or an eligible credit line on UPI. Under the third-party application provider model, Fibe operates the consumer-facing application, while partner banks hold the underlying accounts and manage settlement.
The arrangement allows Fibe to participate in the UPI ecosystem without becoming the bank responsible for customer deposits or settlement. It also creates a route for the company to introduce payment services to people who may not use its lending products.
Fibe, formerly known as EarlySalary, already offers credit cards and other financial products, including fixed deposits, loans against mutual funds and financing for healthcare, education and rooftop solar. The UPI launch adds a high-frequency use case to a business that has historically relied more heavily on credit-related customer interactions.
Why the Move Matters in a Competitive Market
India’s UPI ecosystem has become a major part of everyday retail payments. The system processed a record 25.47 billion transactions in October, according to figures cited by India Fintech. Competition is led by established platforms, with PhonePe and Google Pay accounting for a large share of transaction volume.
For Fibe, the challenge will be persuading users to add another payments application to their phones. Its potential advantage lies in connecting payments with credit products, particularly eligible credit lines on UPI. That could allow customers to access credit at the point of payment rather than treating borrowing and spending as separate activities.
A Wider Consumer Finance Strategy
The launch also fits into Fibe’s broader expansion across financial services. The company’s parent, Social Worth Technologies, received final observations from the Securities and Exchange Board of India in September for a proposed IPO with a fresh issue of up to ₹750 crore. A portion of the proposed proceeds is intended for its lending subsidiary.
A UPI app could help the company maintain more frequent engagement with customers, gather a wider view of their financial activity and introduce additional products over time. Those opportunities will depend on customer adoption, partner-bank arrangements and the company’s ability to maintain payment reliability.
What to Watch Next
Fibe’s entry adds another competitor to India’s crowded UPI market, but approval alone does not guarantee meaningful transaction share. The key indicators will be how many users activate the service, how frequently they make payments and whether the credit-linked features attract customers beyond its existing lending base.



Comments