 By
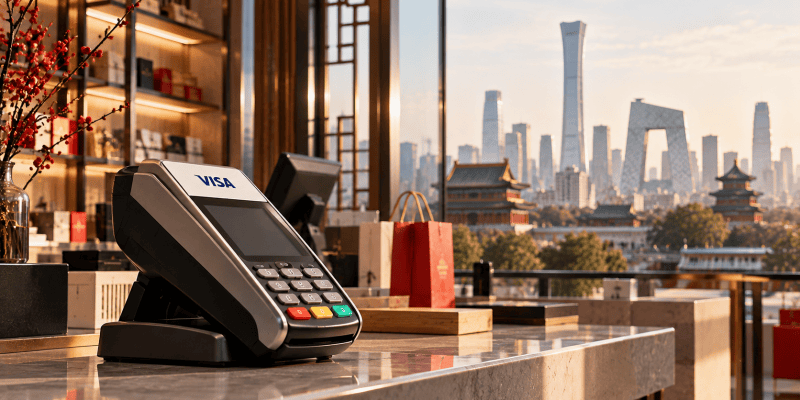
BEIJING, China, Global payments company Visa has received approval from China’s central bank to establish card clearing operations in the country, marking a major development in its long-running effort to access one of the world’s largest consumer payments markets.
The approval, reported on October 13, 2026, comes ahead of a planned meeting between US President Donald Trump and Chinese President Xi Jinping. It represents progress for Visa after years of regulatory and market access challenges in China, where domestic providers have established strong positions in card payments and mobile transactions.
The decision could create a new opportunity for Visa to expand its international payments network, although the company will still face the challenge of competing in a market dominated by established local services.
A Long Pursuit of Market Access
Visa has sought to establish a presence in China’s domestic card clearing market for more than a decade. The country’s payments industry has historically been led by China UnionPay in card transactions, while Alipay and WeChat Pay have become major forces in mobile payments.
Access to domestic clearing infrastructure is important because it enables payment networks to process transactions within a market under local rules. For an international company such as Visa, approval can create a foundation for building relationships with banks, merchants and other financial institutions.
China’s central bank approval represents a significant regulatory step, but commercial expansion will depend on the company’s ability to establish local operations, secure partnerships and meet applicable regulatory requirements.
Competition Extends Beyond Credit Cards
China’s digital payments ecosystem differs from markets where card networks play a more visible role in everyday purchases. Mobile wallets are deeply integrated into shopping, transportation, online services and other consumer activities.
Visa will therefore face competition not only from other card networks but also from established digital platforms that already serve large numbers of users and merchants.
To build market share, the company may need to focus on cross-border commerce, international visitors, overseas spending and partnerships that complement existing payment methods. The scale of the opportunity will depend on the operating permissions granted and the services it can offer.
Why the Approval Matters to Global Fintech
The move could strengthen international payment connectivity between China and the rest of the world. Businesses increasingly depend on reliable payment infrastructure to serve international customers, manage travel spending and support cross-border commerce.
For Visa, access to China could provide an additional route for expanding its global network. However, regulatory approval does not guarantee rapid adoption, particularly in a market where local payment platforms benefit from established customer habits and extensive merchant acceptance.
The decision also comes amid broader discussions about trade and financial cooperation between Washington and Beijing. Greater market access for financial services companies could become part of a wider effort to improve commercial relations, although geopolitical tensions remain a potential source of uncertainty.
What Comes Next
Investors and industry participants will watch for details on Visa’s operating structure, partnerships and timetable for launching services. The company’s ability to establish a competitive local offering will be as important as the regulatory milestone itself.
The approval highlights the continued importance of domestic regulation in global fintech expansion. Even established international networks must adapt to local infrastructure, consumer behaviour and market rules before they can convert access into meaningful commercial growth.


Comments